Executive Summary
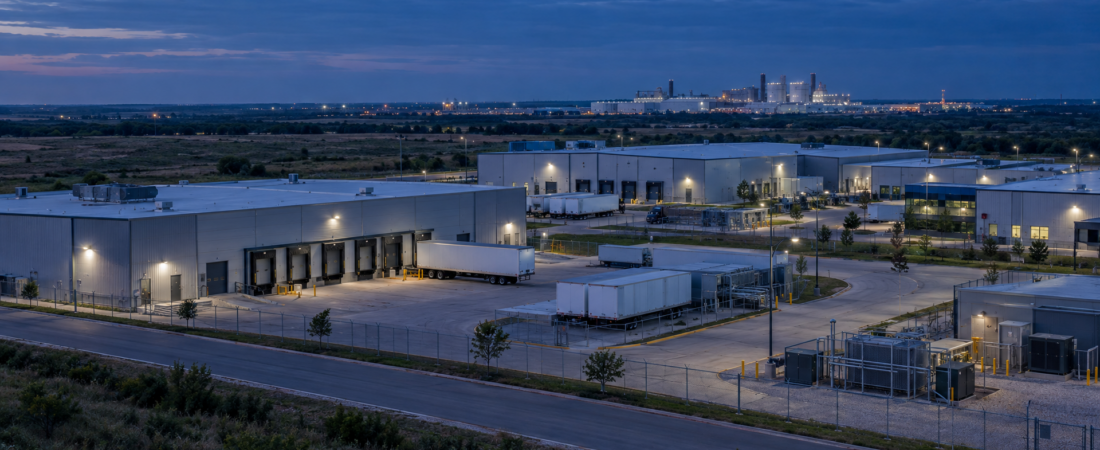
According to the available source information, Taiwan plans to establish dedicated industrial parks in the United States, with a site in Texas already identified to house semiconductor supply chain vendors near major customers. On its face, that is a real-estate and supply-chain development. Strategically, it may be more important than that.
The reported move suggests a shift from one-off overseas expansion toward a more organized clustering approach for Taiwan’s semiconductor ecosystem. Rather than treating each supplier’s US move as an isolated corporate decision, the industrial-park model could lower some of the coordination burden around proximity, logistics, and customer access.
For Asia’s technology supply chains, the significance lies in what this may say about the next phase of semiconductor localization in the US. The issue is no longer just whether major manufacturing assets move closer to end demand. The bigger question is whether the supporting vendor base follows in a structured way, and whether Taiwan can extend parts of its industrial clustering model overseas without weakening the density that has long supported its domestic strength.
Important details remain unclear from the reported information, including project scale, tenant commitments, financing, timelines, and the specific institutions leading the effort. Even so, the direction of travel is meaningful: Taiwan appears to be exploring ways to keep its supply-chain relevance intact as semiconductor and AI hardware production footprints become more geographically distributed.
Watch the Short Brief
Watch this short visual briefing for the key strategic implications behind the story.
Key Developments
According to the source summary, Taiwan plans to build dedicated industrial parks in the US for semiconductor supply chain vendors. A site in Texas has already been found or secured, based on the reported information.
The stated purpose is to place suppliers closer to major customers in the US market. That matters because semiconductor manufacturing is not only defined by anchor facilities such as fabrication plants or assembly lines, but also by the density of nearby materials, components, services, and specialty vendors that support them.
The currently available information does not identify which suppliers may enter the proposed parks. It also does not provide confirmed details on land size, capital commitments, construction schedules, operating models, or whether the Texas site is the first of multiple planned locations.
TSMC and Nvidia are listed in the source information as related companies, but the available reporting does not indicate that either company is directly involved in the industrial park initiative. Their relevance is broader: TSMC sits at the center of Taiwan’s semiconductor ecosystem, while Nvidia is a key name in AI hardware demand. In this case, both are best understood as part of the surrounding industry context rather than confirmed participants.
The development sits at the intersection of Taiwan-US technology ties, semiconductor supply-chain realignment, and the growing push to position manufacturing capacity closer to North American demand centers.
Strategic Analysis
The most important implication of the reported plan is structural. Taiwan’s semiconductor advantage has long depended not just on individual companies, but on clustered industrial organization. A dense network of specialized suppliers, engineering services, logistics support, and manufacturing know-how has helped reduce friction across the production chain. That model is difficult to reproduce quickly in overseas markets.
If Taiwan is now supporting, facilitating, or otherwise advancing a dedicated industrial-park concept in the US, it may indicate recognition that isolated facility announcements are not enough. A fab, packaging line, or electronics assembly site can be built abroad, but without supplier density nearby, costs can rise, response times can lengthen, and dependence on long-distance shipping can remain high for critical inputs.
That is why the industrial-park concept matters more than the Texas site alone. The Texas location is the reported fact. The larger strategic question is whether this becomes a platform for reproducing part of Taiwan’s ecosystem logic on US soil.
For the US, such a model could improve the practicality of semiconductor localization. One of the recurring challenges in onshoring or friend-shoring advanced manufacturing has been that production assets can move faster than the supplier web around them. When suppliers remain fragmented across geographies, the result is often a partial rather than fully functional local ecosystem. Industrial parks designed specifically for semiconductor vendors could help narrow that gap.
For Taiwan, the issue is more complex. The opportunity is clear: staying close to customers as production footprints globalize can help Taiwanese suppliers defend relationships, shorten delivery cycles, and remain embedded in next-generation manufacturing programs. In an industry where proximity often influences responsiveness and engineering collaboration, that matters.
But there is also a strategic balancing act. Taiwan’s leverage in semiconductors has been closely tied to the concentration of expertise and supply-chain density at home. If too much supporting capacity migrates abroad, Taiwan could eventually face questions about ecosystem dilution. That does not mean overseas clustering is negative. It does mean the long-term value lies in selective extension, not uncontrolled hollowing-out.
This is also relevant to AI infrastructure. The source material does not state that the parks are tied directly to AI server deployments or specific accelerator programs. However, as a matter of industry analysis, any move that brings semiconductor suppliers closer to US manufacturing and systems demand could become increasingly relevant in an AI-driven hardware cycle. AI infrastructure places heavy demands on semiconductors, advanced components, power systems, thermal management, and high-value electronics integration. Supplier proximity can matter when production schedules tighten and customization requirements increase.
Texas is also notable in strategic terms. Even without further confirmed details, a Texas site suggests interest in locating near a major US industrial base with existing semiconductor and electronics relevance. If the project advances, site selection could prove as important as the park concept itself, because the success of supplier clustering depends on labor access, infrastructure, permitting conditions, logistics, and adjacency to customer operations.
Another implication is competitive signaling. If the reported plan moves forward, other Asian technology economies may watch closely. Taiwan has one of the world’s deepest semiconductor supplier ecosystems. A credible effort to transplant part of that ecosystem into the US would not simply be a commercial development; it could become a reference point for how export-oriented manufacturing clusters adapt to geopolitical pressure and customer localization demands.
That does not mean a broad relocation wave is imminent. The available information is too limited to support that conclusion. But it does suggest that supply-chain adaptation is entering a more organized phase, one in which industrial geography may be shaped not only by individual company capex decisions, but by clustering strategies designed to preserve ecosystem efficiency across borders.
Investor Takeaway
Investors should treat this development as an early but meaningful signal in semiconductor supply-chain reconfiguration. The confirmed core of the story is narrow but important: Taiwan plans dedicated US industrial parks for semiconductor vendors, and a Texas site has already been identified according to the report. The open question is whether this becomes an operational cluster with committed tenants, capital backing, and repeatable expansion.
The most useful lens is not real estate alone, but ecosystem formation. If follow-on announcements show Taiwanese materials, components, testing, equipment-support, or specialty manufacturing suppliers setting up in or around the planned parks, that would suggest the model is gaining traction. If the initiative remains limited to site preparation without visible tenant commitments, its strategic significance would be lower.
What matters next are the details the initial report does not yet provide. Investors should monitor whether specific suppliers are named, whether project funding and timelines are disclosed, and whether additional US locations are proposed. Those signals would help distinguish between an exploratory concept and the beginning of a durable cross-border industrial platform.
There are also execution risks. US operating costs, labor constraints, permitting complexity, and the challenge of recreating Taiwan-style supplier density abroad could all slow progress. Even if customer logic supports localization, semiconductor supply chains do not become efficient simply because land is available. Cluster success depends on sustained participation from multiple layers of the ecosystem.
The broader strategic relevance, especially for Asia-focused technology intelligence, is clear. Semiconductor competition is increasingly about where ecosystems sit, not just where flagship plants are built. If Taiwan can extend parts of its supplier network into the US while preserving its domestic core, it may strengthen its role in a more geographically distributed industry. If not, the result could be a costlier and less cohesive supply chain on both sides of the Pacific.
For now, the Texas site should be viewed as a potential marker of that next phase. The reported initiative is still early, but it points to a central issue for the AI era: the future of semiconductor power will depend not only on chips, but on who can successfully move entire industrial ecosystems closer to demand without losing the advantages of scale, specialization, and coordination that made those ecosystems valuable in the first place.