Executive Summary
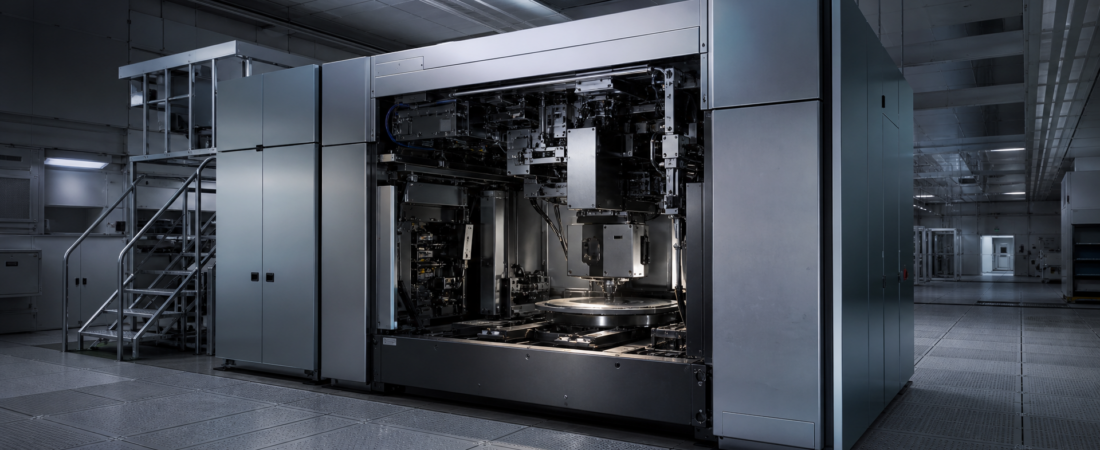
ASML’s lead in advanced lithography appears set to deepen, according to the available source information. The report says ASML’s existing extreme ultraviolet, or EUV, machines are sold out through 2027, while major customers including TSMC, Samsung, and SK Hynix have set firm dates to adopt the company’s next-generation High NA systems for production beginning in 2028.
That matters well beyond equipment ordering. Taiwan and South Korea sit at the center of advanced logic and memory production, two segments that are increasingly tied to AI infrastructure demand. If the reported timelines hold, the next phase of leading-edge semiconductor manufacturing in Asia will remain closely linked to one Dutch supplier’s roadmap, delivery schedule, and pricing power.
The source package does not provide detailed node plans, shipment volumes, or company-by-company capital expenditure breakdowns. Even so, the reported customer commitments are strategically significant. They suggest that some of the industry’s most important Asian manufacturers are willing to lock in very expensive next-generation lithography capacity years in advance, reinforcing the importance of equipment access as a core competitive variable in semiconductors.
Watch the Short Brief
Watch this short visual briefing for the key strategic implications behind the story.
Key Developments
According to the reported information, ASML’s current-generation EUV systems are sold out through 2027. That points to continued demand for leading-edge lithography tools even before High NA enters broader production use.
The same report says TSMC, Samsung, and SK Hynix have set firm dates to adopt ASML’s High NA tools for production starting in 2028. These companies are central to Asia’s semiconductor position: TSMC in advanced foundry manufacturing, Samsung across foundry and memory, and SK Hynix in memory, particularly where AI-related demand has increased attention on high-performance products.
The source summary also puts the price of each High NA tool at about $400 million. At that level, High NA is not just a technology upgrade. It is a large capital allocation decision that only a limited number of chipmakers can absorb at scale.
Geographically, the report highlights a concentrated supply-chain map spanning the Netherlands, Taiwan, South Korea, and the United States. ASML supplies the equipment. Asian manufacturers are among the most important end users. US technology policy and end-market demand remain influential in shaping the broader environment around advanced chip production.
Intel and Micron are named in the source package as related companies, but the available information does not specify their High NA production adoption timelines. For now, the clearest reported commitments are those tied to TSMC, Samsung, and SK Hynix.
Strategic Analysis
The immediate takeaway is not simply that ASML has strong demand. It is that lithography remains one of the clearest control points in the advanced semiconductor value chain.
When leading manufacturers in Taiwan and South Korea commit years ahead to a new lithography platform, they are not just buying tools. They are aligning process development, fab planning, supplier coordination, and capital budgets around the expected availability of that platform. In practice, that can make equipment timing as important as product design in determining who reaches production targets on schedule.
For Asia, this is especially important because the region’s semiconductor weight is concentrated at the leading edge. TSMC’s foundry role and South Korea’s memory leadership already make both economies central to AI hardware supply chains. If their next production transitions depend on High NA deployment from 2028 onward, then access to ASML’s tools may become an even more important differentiator between companies that can maintain frontier manufacturing and those that cannot.
The reported sellout of existing EUV tools through 2027 also suggests that demand for advanced manufacturing equipment remains firm. Semiconductor spending is often cyclical, and capital intensity can swing sharply with end-market conditions. But multiyear visibility for EUV orders may indicate that customers still see enough demand in advanced compute, memory, and AI infrastructure to justify committing capital despite long lead times and very high tool costs.
That does not mean all execution risk disappears. In fact, the opposite may be true. As more value in the chip ecosystem depends on a narrow set of advanced production steps, any delays in tool readiness, installation, throughput, or customer qualification could have ripple effects across multiple segments. Those risks would not be limited to foundries. They could extend to memory producers, cloud infrastructure buildouts, and AI server supply chains that depend on steady progress in both compute and memory performance.
Another implication is competitive concentration. At roughly $400 million per reported tool, High NA adoption raises the threshold for participation at the frontier. The companies most able to absorb that cost are also the ones most likely to capture early learning effects, process know-how, and customer confidence. That could reinforce the advantage of the largest manufacturers while making it harder for smaller rivals to remain technologically relevant at the leading edge.
This matters in Asia because semiconductor leadership in the region is already concentrated in a small number of national champions. If next-generation lithography becomes even more capital intensive, the result may be a deeper divide between top-tier fabs and the rest of the market. For governments, that raises familiar questions about industrial policy, technology access, and the resilience of national semiconductor strategies. For companies, it raises a more immediate question: whether they can justify the spending required to keep pace.
Geopolitics also remains inseparable from this story. Advanced lithography tools sit at the intersection of commercial demand and strategic policy. With ASML based in the Netherlands and key customers in Taiwan and South Korea, the High NA transition reinforces a supply-chain structure that is efficient but concentrated. Any future changes in export controls, alliance politics, or technology restrictions could affect how quickly tools move across borders and which companies receive priority access.
That does not mean disruption is imminent. But it does mean investors should view High NA not just as a product cycle. It is also a geopolitical asset class inside the semiconductor stack, where manufacturing capability, policy sensitivity, and capital intensity increasingly overlap.
Investor Takeaway
For investors, this looks more like a confirmation signal than a standalone surprise. The reported facts strengthen the view that advanced semiconductor competition remains anchored in access to a very small set of critical tools, and that Asia will remain central to how those tools translate into commercial chip output.
The most important point to monitor is execution. If ASML’s current EUV systems are indeed sold out through 2027 and major Asian customers are targeting High NA production from 2028, then delivery schedules, installation progress, and manufacturing readiness become key variables. Investors should watch whether those timelines hold or begin to slip.
Capital spending is the second major issue. Reported tool costs of around $400 million imply meaningful budget commitments from TSMC, Samsung, and SK Hynix. Future company disclosures may provide a clearer view of how quickly those investments scale and whether High NA spending changes broader priorities across fabs, memory lines, or packaging ecosystems.
Third, investors should watch whether High NA adoption remains limited to initial production stages or expands into a broader manufacturing standard over time. The current source information supports reported adoption dates beginning in 2028, but not a full industry timetable. That distinction matters. Early deployment is not the same as widespread use across multiple nodes, products, or business segments.
Policy risk should also stay on the list. Advanced lithography is likely to remain a sensitive area for governments, especially where semiconductor leadership intersects with national security and AI infrastructure. Any shift in export-control frameworks, licensing conditions, or alliance coordination could affect tool flows and capacity planning.
Finally, Intel and Micron remain relevant names to monitor in the wider competitive landscape, but the source package does not provide enough detail to draw conclusions about their specific High NA timelines. For now, the clearest strategic read comes from Asia: the region’s leading chipmakers appear willing to commit early and heavily to the next lithography step, and that may help define the pace and structure of advanced semiconductor competition in the years immediately ahead.