Latest posts
-
AMEC’s 100-Tool Roadmap and China’s Semiconductor Equipment Push
AMEC plans to expand from 54 to more than 100 high-end semiconductor equipment types within five years. The strategic test is whether broader coverage translates into qualification, reliable fab use, and stronger domestic supply-chain resilience.
-
xLight’s EUV Light-Source Bet Targets a Critical Semiconductor Bottleneck
xLight is targeting one of chipmaking’s hardest chokepoints: the EUV light source. If the approach proves valid, it could influence fab productivity, tool economics, and advanced AI chip scaling.
-
Intel’s EMIB-T Delay to 2027 Reinforces TSMC’s Advanced Packaging Lead
Intel’s reported EMIB-T delay suggests TSMC’s CoWoS may remain the main high-volume AI packaging option for longer. The result is continued concentration risk across the semiconductor supply chain.
-
ASE’s Higher 2026 Capex Signals Rising Pressure in AI Packaging
ASE’s higher 2026 capex points to more than a spending update. The key signal is that AI demand may be tightening packaging and test capacity, shifting attention to Taiwan’s backend semiconductor layer.
-
Samsung’s Memory Warning Raises New Questions for AI Hardware Supply Through 2028
Samsung is warning that AI demand could keep the global memory market tight through 2028. The implication is a longer bottleneck across servers, devices, and AI infrastructure, with downstream cost pressure.
-
OpenAI’s ‘Abundant Intelligence’ Thesis and the Economics of AI Infrastructure
OpenAI’s latest statement frames AI infrastructure as a way to lower the cost of intelligence, not just expand scale. If cheaper AI drives broader enterprise adoption, it could support continued spending across the hardware and data center stack.
-
UMC’s $5 Billion Expansion Plan Highlights a Broader Shift in AI Chip Infrastructure
UMC’s reported 5 billion dollar expansion points to a broader shift in AI semiconductor value toward advanced packaging and silicon photonics. The opportunity is wider relevance in the AI stack, but execution and utilization remain the key risks.
-
Kumamoto Earthquake Highlights Concentration Risk in Japan’s Chip and Auto Supply Chains
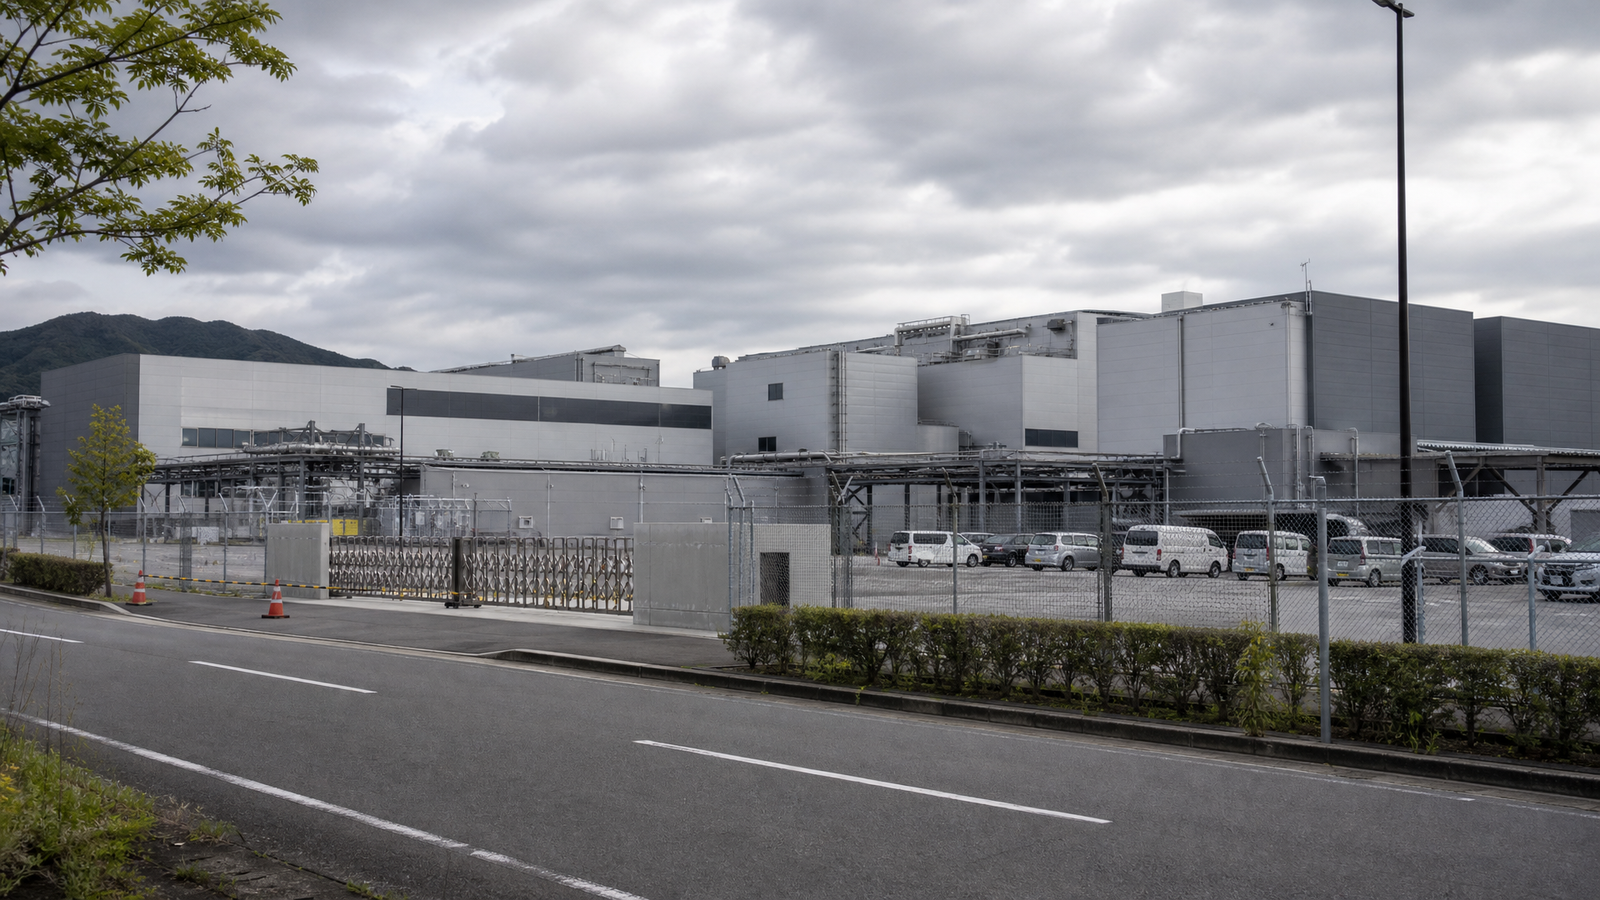
Japan’s Kumamoto earthquake is more than a local disruption. Reported suspensions at Renesas, Sony, and Tokyo Electron highlight how concentrated semiconductor and electronics capacity can turn a regional shock into a wider industrial risk.
-
Asia’s Cautious M&A Start Still Points to AI Infrastructure Strength
Asia’s M&A market opened cautiously, but AI-linked digital infrastructure and compute capacity continue to attract resilient capital. Malaysia stands out as a Southeast Asia market to watch.
-
Seoul Calls Emergency Market Review After Semiconductor-Led Selloff
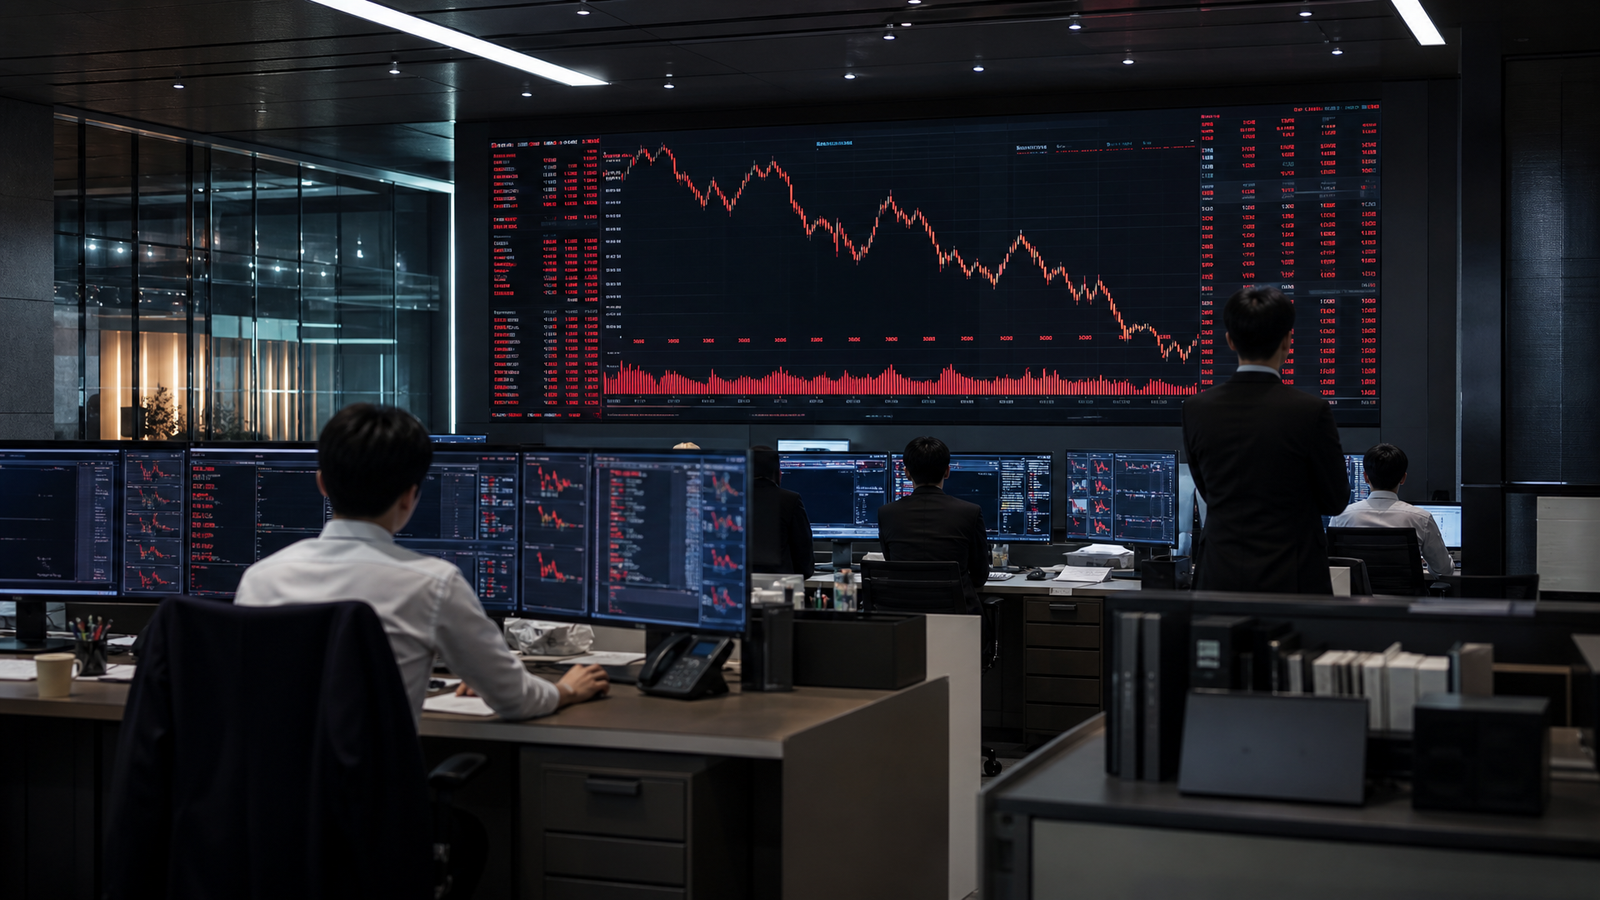
South Korea’s emergency market review signals that a chip-led selloff is being read through two external pressures: China competition and US tech funding concerns. The result is greater sensitivity in Korean chip valuations to cross-border industrial and capital-market conditions.